
Mortgage Broker Camberwell | Local Expertise
Contact Us
P. 1300 671 801
M. 0422 264 558 (Alan Harrosh)
M. 0407 877 115 (Mark Harrosh)
E. admin@roshpartners.com.au
A. Level 1, 793 Burke Road, Hawthorn East VIC 3123.
Camberwell connections spanning generations. Personal mortgage advice backed by more than 20 years of industry experience.
Looking for a mortgage broker in Camberwell who understands both the lending process and the local area? At Rosh Partners, our connection to Camberwell goes well beyond providing home loans.
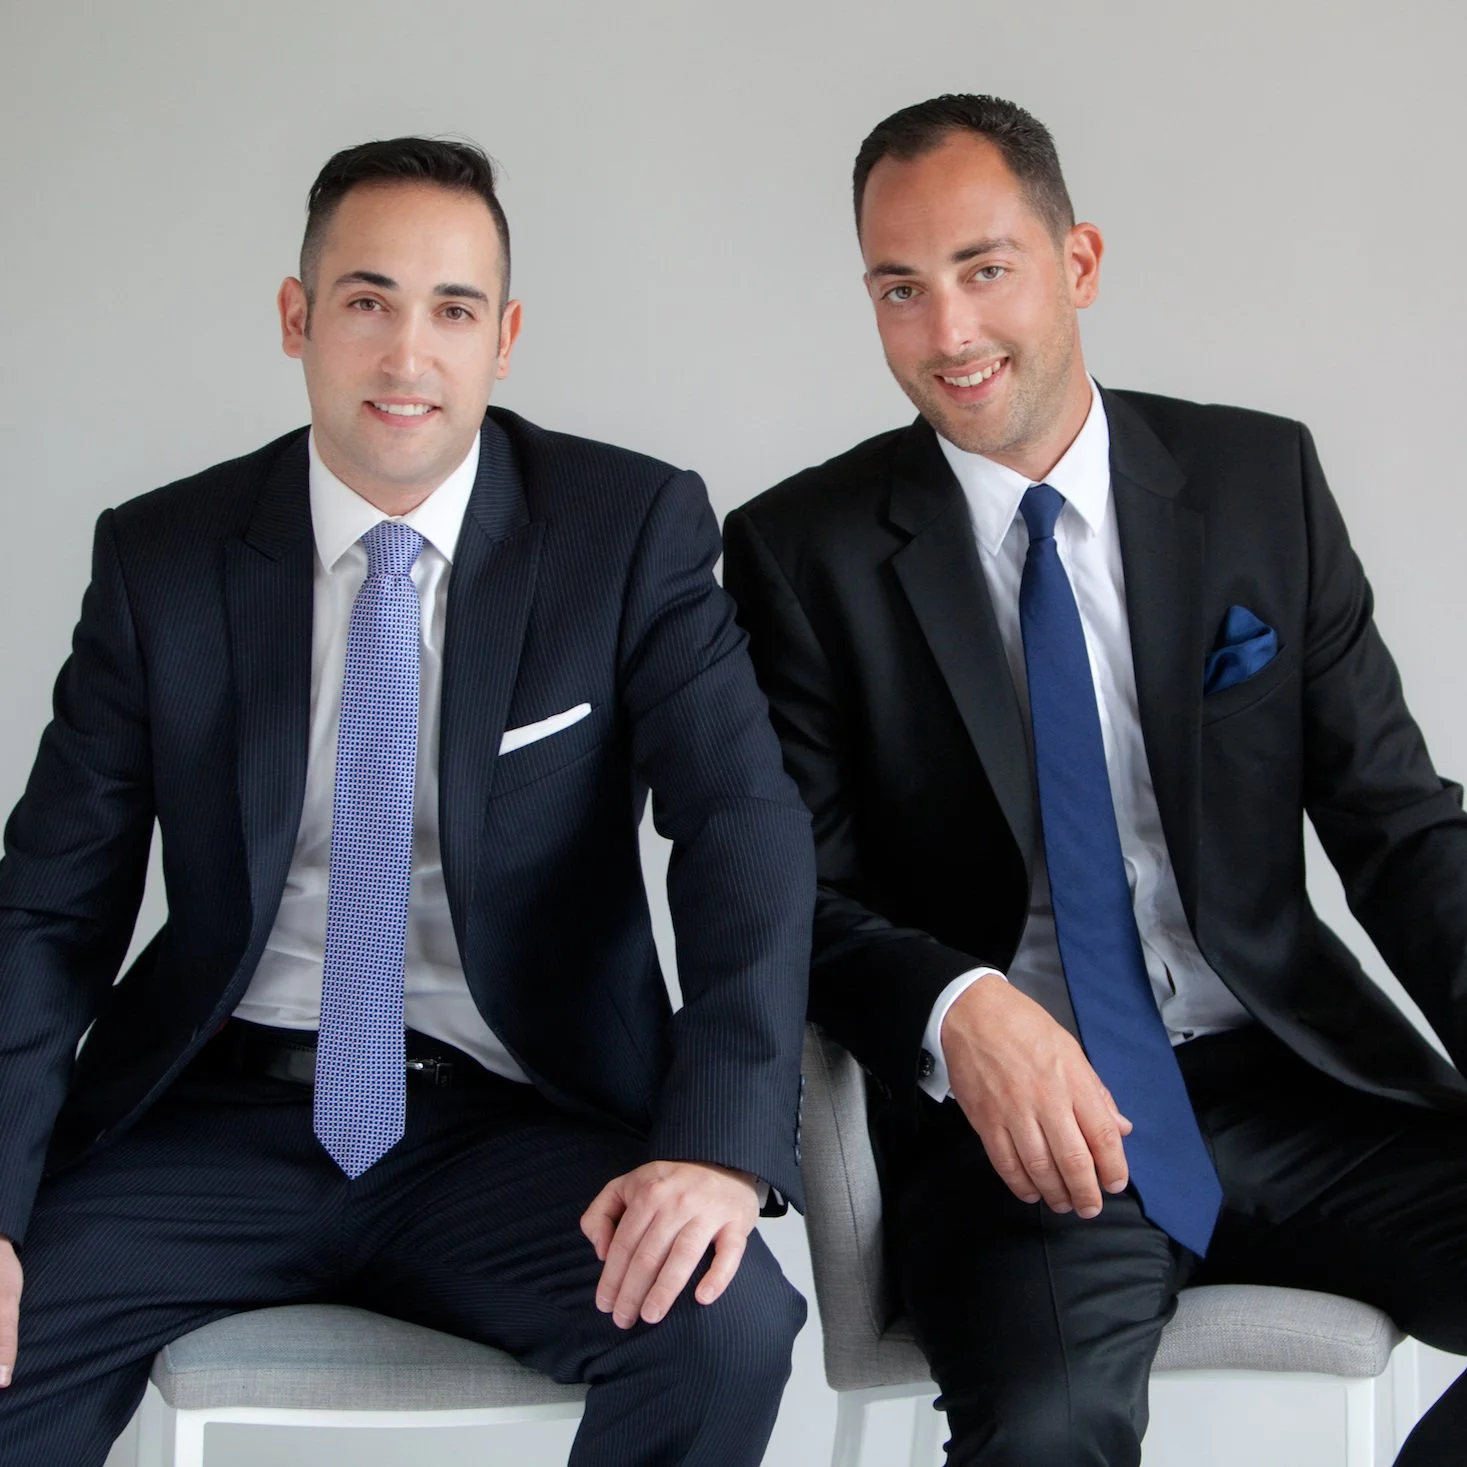
Brothers and Rosh Partners co-founders Alan and Mark Harrosh grew up in Camberwell, and their parents still live in the family home today. It's an area we know personally, with longstanding family connections and more than two decades of experience assisting borrowers with their property finance needs.
Our Hawthorn East office at 793 Burke Road is conveniently located on the Camberwell border, making it easy to arrange a local appointment. We also assist clients throughout Melbourne by phone and online.
Speak directly with an experienced mortgage broker who knows Camberwell and understands the importance of getting your home loan structure right.
Home Loans and Property Finance in Camberwell
-
Refinancing an Existing Camberwell Home Loan
If you've owned your property for several years, your mortgage may no longer be as competitive as it could be.
We review your existing interest rate, loan balance, remaining term, fees and loan features before comparing suitable alternatives.
Importantly, refinancing doesn't automatically mean starting another 30-year loan term. Where appropriate, we can structure the new mortgage around your existing remaining term to avoid unnecessarily increasing the total interest payable over the life of the loan.
-

Purchasing or Upgrading Your Family Home
Buying your next home can be more complicated when you already own a property.
You may need to coordinate a sale and purchase, arrange finance before your existing property sells or consider whether bridging finance is appropriate.
We help assess your borrowing capacity, available equity, deposit requirements and the lending options available for your proposed purchase.
-
First Home Buyer Loans and Pre-Approval
Buying your first home in Camberwell or the surrounding suburbs involves more than simply finding a competitive interest rate.
We help first home buyers understand their borrowing capacity, deposit requirements, upfront purchase costs and available government assistance, including eligibility for the Australian Government 5% Deposit Scheme.
We can also arrange home loan pre-approval, helping you establish a realistic budget before making an offer or bidding at auction.
-
Construction & Renovation Loan Finance
For homeowners who love their Camberwell location but need more space, renovating or extending an existing property may be an alternative to moving.
Depending on your circumstances, finance options can include accessing existing equity, increasing your current mortgage or arranging a construction loan for substantial building works.
We can explain how lenders assess renovation costs, valuations, available equity and construction progress payments.
Why use Rosh Partners as your Mortgage Broker in Camberwell?
A Genuine Connection to Camberwell
Camberwell isn't simply another suburb we service. It's where our founders grew up and where their family continues to have strong ties. Combined with our mortgage broking experience, this personal connection gives us an understanding of the area and the changing financial needs of homeowners across different stages of life.

Experienced Advice for Established Homeowners
Many borrowers already have a mortgage but haven't reviewed its competitiveness or structure for several years. We help homeowners assess their existing loans, compare refinancing opportunities, access available equity and consider finance for renovations or their next property purchase.

Mortgage Structures That Work Beyond Settlement
The right mortgage isn't necessarily the one with the lowest advertised rate. We consider repayment types, loan terms, offset accounts, redraw facilities and the flexibility to make additional repayments. Our aim is to recommend a structure that supports both your immediate needs and longer-term financial plans.

Direct Access to Your Mortgage Broker
You'll deal directly with your mortgage broker throughout the application process, from the initial discussion and lender selection through to approval and settlement. We also offer ongoing assistance and periodic loan reviews, helping you assess whether your mortgage remains suitable as circumstances and lending conditions change.
Frequently Asked Questions - Camberwell Mortgage Brokers
-
Yes. When refinancing, it's often possible to select a loan term that reflects the remaining term of your existing mortgage, subject to lender approval.
For example, if you have 23 years remaining on your current home loan, we can investigate refinancing over a similar term rather than automatically resetting the mortgage to 30 years.
Extending a loan term can reduce the required monthly repayments but may increase the total interest paid over time.
At Rosh Partners, we compare the interest rate, fees, repayment structure and loan term together, helping you understand the overall cost of refinancing rather than focusing solely on the monthly repayment.
-
Potentially, yes. If your property has increased in value or you've reduced your mortgage balance, you may have available equity that can be used towards renovations or an extension.
The amount you can borrow will depend on the property's valuation, existing debt, your financial circumstances and the lender's credit policy.
For smaller projects, accessing equity through a mortgage increase may be suitable. Larger structural renovations or extensions may require a construction loan with funds released progressively as building work is completed.
We can review the available options and help you understand the costs and lending requirements before you commit to a building project.
-
Bridging finance may allow you to purchase your next property before your existing home has been sold.
Depending on the lender, the arrangement may temporarily combine your existing mortgage with the finance required for the new purchase. Once your original property sells, the sale proceeds are used to reduce the outstanding debt.
Lenders assess bridging finance differently, including the amount of equity required, acceptable loan terms, repayment arrangements and the proposed exit strategy.
We can compare bridging finance with alternatives such as selling first, negotiating settlement dates or using available cash and equity.
-
Yes. We can assess whether available equity in your existing property could contribute towards the deposit and purchase costs of an investment property.
Where appropriate, separate loan splits can help distinguish borrowings used for different purposes. We also compare investment lending options, including interest-only and principal-and-interest repayments, variable and fixed interest rates, and offset account availability.
Borrowing against your existing home increases your financial commitments and may place that property at additional risk. We explain the lending implications and recommend obtaining independent tax advice about deductibility and ownership structures.
-
No. While our Hawthorn East office is conveniently located on Burke Road near the Camberwell boundary, most of the mortgage process can be completed remotely.
We offer telephone and online appointments, electronic document collection and digital loan applications where supported by the lender.
If you'd prefer to meet in person, appointments can be arranged at our Hawthorn East office.
You'll deal directly with your mortgage broker, regardless of whether we meet face-to-face or manage the process online.